Episode Transcript
[00:00:00] Speaker A: Welcome back to behind the Scams. I'm Nick.
[00:00:03] Speaker B: And I'm Sue. Today we are taking a deep dive into the financial plumbing that powers global cybercrime. When people think about massive online scams, they usually picture complex computer hacks or anonymous operators running boiler rooms in distant corners of the world. But international fraud syndicates face one massive operational bottleneck once they trick a victim into handing over their life savings. A how do they actually move that stolen cash out of a domestic bank account and into their own hands without getting caught immediately?
[00:00:33] Speaker A: The answer isn't a high tech computer virus. It's ordinary bank accounts right here in local communities.
It's the unemployed worker who thinks they found a remote job, the retiree who believes they are helping an online companion, or in some cases, trusted professionals who decide to monetize their access to the banking system.
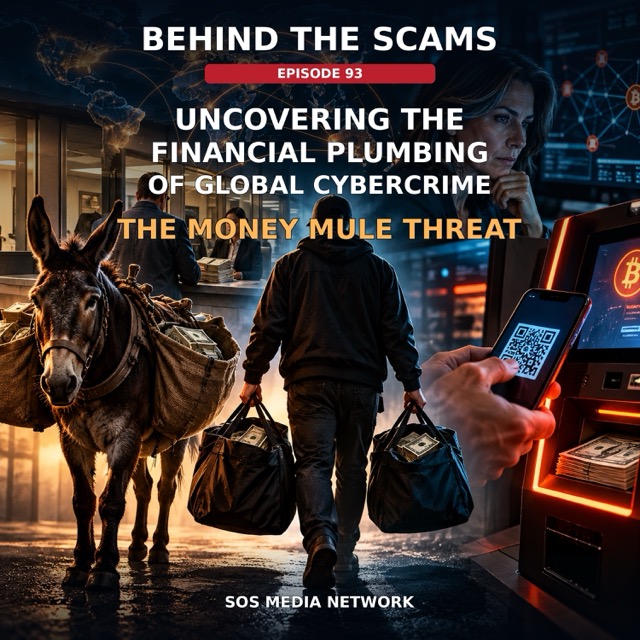
In financial intelligence, these pass through account holders are called money mules.
Today we're tracing the full trail of how fraud proceeds move from victims through mules, peer to peer payment apps, shell companies and crypto exchanges.
[00:01:07] Speaker B: To understand how severe this problem has become, look at Samuel d. Marcus, a 33 year old former Department of Defense logistics specialist from Orland, Pennsylvania. Prosecutors say that while holding a trusted federal position, Marcus became a high capacity money mule for a Nigeria based fraud network.
[00:01:25] Speaker A: What makes the Marcus story especially instructive is how the relationship reportedly evolved.
Prosecutors say Marcus was first targeted in a romance fraud in late 2022 and early 2023. By July 2023, however, he was knowingly helping the same Nigeria based network that had victimized him. That progression from target to participant to repeat facilitator shows why investigators focus on what Emile knew speech, not simply how the contact began.
[00:01:55] Speaker B: The network used aliases including Rachel Jude and Ned McMurray. According to the Justice Department. Its schemes included romance fraud, cyber fraud, tax fraud, financing fraud, and business email compromise. Marcus, then a Department of Defense logistics specialist, moved millions of dollars through personal and business accounts between roughly July 2023 and December 2025.
[00:02:17] Speaker A: And this was not merely a matter of forwarding a payment. Prosecutors say he converted victim funds into cryptocurrency, routed money to foreign accounts, and supplied fraudulent invoices to banks to make the transactions look legitimate. Those invoices matter because they are evidence of concealment. Paperwork was being created to give stolen proceeds a false business purpose.
[00:02:40] Speaker B: The most damaging fact may be what happened after authorities intervened.
Federal agents told Marcus that money passing through his accounts had been stolen and that his transfers were consistent with money laundering.
Prosecutors say he nevertheless continued Once someone receives that kind of explicit warning, the claim that the transactions merely seemed unusual becomes far harder to sustain.
[00:03:05] Speaker A: Marcus pleaded guilty on July 6, 2026, to one count of concealment money laundering.
At the time of this recording, sentencing was scheduled for October 16, 2026. The offense carries a maximum possible penalty of 20 years in prison, three years of supervised release, and a $250,000 fine. That is a maximum, not a prediction of the sentence the court will impose.
[00:03:30] Speaker B: The network targeted Americans through romance, cyber tax financing and business email compromise schemes.
Victims were directed to accounts controlled by Marcus and other mules. Once funds arrived, Marcus converted proceeds into cryptocurrency, moved money into foreign accounts, and used fraudulent invoices to make transactions appear legitimate.
[00:03:51] Speaker A: Law enforcement and financial intelligence analysts generally divide money mules into three distinct unwitting, witting and complicit. Understanding how scammers recruit people into each category reveals why this infrastructure is so difficult to tear down.
Lets start with the unwitting mules, people who have no idea they are participating in a crime. One of the most common recruitment tools is the work from home job scam. Job seekers browse legitimate job portals like LinkedIn or Indeed, and find listings for titles like Regional Payment Processor, Logistics Quality Inspector or Executive Administrative Assistant. The entire interview process happens remotely through messaging platforms like Telegram.
When tired, the employee is told their main duty is to receive client payments into their personal checking account, keep a 5 to 10% commission as their salary, and forward the rest to suppliers using peer to peer payment apps or cryptocurrency kiosks. The employee believes they are performing legitimate corporate work. In reality, every deposit into their account is stolen money coming from a victim of a tech supporter or real estate wire scam. A similar recruitment vector occurs in the romance scam space.
Consider the federal case of Cheryl White, a 58 year old woman from Maine. White connected online with an individual who claimed to be involved in international work. Over time, her online companion built a relationship of trust and eventually asked her to help receive and move money.
[00:05:16] Speaker B: Come on. That just makes me sick that that story is like almost every story that you hear and that that just breaks my heart for these, for these people who are unsuspecting. But, but here's where it really hits. You know, it gets complicated because as in so many of these cases, what you just described with people like Cheryl White, people who are otherwise really normal, innocent people, these people have then been turned into federal money mules, which I mean when we're talking about money that was probably already laundered I mean. Right.
[00:05:47] Speaker A: Yeah, exactly. I mean, that's the whole point of money mules, right? They're trying to hide the money, and people are just becoming a part of this machine and sometimes completely unaware that they're doing that. But I want to talk about White. Right. So as far as. So White, in this case, was given the task of receiving international wire transfers, which were often coming from these elder fraud scams.
They would then take a commission and then forward those funds to these third parties that was either by. Via bank or via, like a cryptocurrency transaction, which now makes this. This trail almost impossible to follow for federal authorities. And she received over $1.2 million before being charged with federal wire fraud. And she was sentenced to 37 months in federal prison and three years supervised release.
[00:06:33] Speaker B: I mean, that. That is really tough because, you know, the people behind the curtain, the ones who are really pulling the strings here, I mean, most of these cases and from the. Most of the research that we found, really go to great lengths to cover their tracks. Right.
So often, you know, they're using people like you mentioned, unwitting mules, and they're very careful to keep them at arm's length, so. So that they themselves aren't being found. And oftentimes that means, you know, kind of putting in place, you know, a lot of different levels of protection for themselves. And, you know, often that's like a lot of intermediaries or people who are. I mean, to put it simply, like, they're almost like fall guys, people that. Who could be thrown under the bus, if you will.
[00:07:17] Speaker A: Yeah, and that goes back to, like, the mules, Right? I mean, at that point, they just become like fall people, and then everybody who's involved, they just become like the fall guy. Right.
[00:07:25] Speaker B: White bought prepaid debit cards and gave the account numbers to the person she had met online. After the cards were loaded with money, she withdrew the funds, bought money orders, deposited those money orders into her bank account, and days later, withdrew and mailed most of the cash to an address she had been given. The $7,340 came from FEMA payments issued on fraudulent disaster relief claims.
[00:07:48] Speaker A: But this case also shows the line between being deceived and becoming willfully involved. Court records say two banks had already closed White's accounts because of similar activity, and one bank specifically told her that the deposits and withdrawals were part of a fraud scheme. She opened another account and continued.
White admitted that she knew the money came from some kind of crime.
[00:08:10] Speaker B: She pleaded guilty in May 2022.
In April 2023. A federal judge sentenced her to three years of probation and ordered her to pay $7,340 in restitution to FEMA.
The lesson is not that every romance scam victim is a criminal. It is that repeated warnings, closed accounts, implausible explanations and continued transfers can transform the legal picture.
[00:08:36] Speaker A: There is another Pennsylvania case that makes the escape relation even more dramatic. Emily zoul Vance, a 65 year old woman from Coatesville, admitted helping foreign scammers move nearly $2 million from romance scams and business email compromise schemes. The person directing her used the name David Thomas, a man she had never met in person.
[00:08:58] Speaker B: The money arrives in almost every form imaginable. Wire transfers into her accounts, checks and cashiers, checks and and even cash mailed or shipped directly to her home.
David Thomas would tell her when a payment was coming. She would watch the account, deposit whatever arrived, and then send the money wherever he instructed, often after converting it into cryptocurrency.
[00:09:20] Speaker A: What makes the scale so striking is how many banking relationships she cycled through during the charge period. Zawaki used at least 20 accounts at 14 financial institutions, both in her own name and through a shell company called Emily Enterprises. Banks repeatedly closed her accounts because they suspected fraud, and some explicitly told her why.
[00:09:41] Speaker B: Then came two unmistakable warnings. Federal agents told her in October 2022 that she was helping scammers defraud people and could be prosecuted if she continued. They warned her again in March 2023.
Yet prosecutors say she kept moving money until July 2025.
By then, individual victims and businesses had lost approximately $1.9 million through her activity.
[00:10:05] Speaker A: In August 2026, Zawacki pleaded guilty to nine counts of wire fraud and four counts of mail fraud. Her story captures the entire spectrum. We are discussing an unseen online controller, packages and payments from strangers, repeated bank closures, cryptocurrency conversion, a shell company and continued activity after direct law enforcement warnings.
[00:10:29] Speaker B: And for families, imagine how those signs might have appeared at home. Texts and cash arriving from unknown people, constant monitoring of account balances, repeated openings and closings of bank accounts, and urgent instructions from a person no one had ever met. Any one event might be explained away. Together, they reveal a pattern that demands intervention.
[00:10:51] Speaker A: Recruiters look for people who need money, connection, purpose or reassurance.
That can include job seekers, college students, newcomers unfamiliar with the banking system, older adults who are lonely people under financial stress, and anyone emotionally invested in an online relationship.
None of those traits make someone foolish. They simply give a skilled manipulator something to work with Some recruits believe they have found easy, remote work.
[00:11:22] Speaker B: Others believe they are helping a romantic partner, a friend overseas, or a relative facing an emergency.
A person may also be attracted by the promise of quick commissions. When bills are overdue, the scammer adapts the story to whatever the target needs most at that moment.
[00:11:41] Speaker A: The process usually starts small. The recruiter asks for one harmless looking favor, praises the person for being trustworthy, and then gradually raises the stakes. Once money has moved, the recruiter may use guilt, fear, affection, or threats to keep the person involved. That gradual escalation is why a loved one may not recognize how serious the situation has been.
[00:12:07] Speaker B: Then you have waiting or complicit mules like Samuel Marcus, who know or strongly suspect that the funds moving through their accounts are illicit. Scammers actively recruit witty mules on dark Web forums and encrypted messaging channels, offering them a fixed percentage of every transaction. These individuals often believe that because they aren't the ones directly tricking the victims, they can't be held criminally responsible. As we'll discuss later, federal law proves them completely wrong.
[00:12:34] Speaker A: Before we trace the transaction, it is worth asking why overseas scammers need money mules at all? Why not simply tell every victim to send money directly to another country?
Because a domestic account looks safer and more believable, A victim may hesitate to wire money overseas, but an account at a familiar American bank can appear legitimate.
It may be held by a real person with a local address, established credit, and years of ordinary account activity. The mule lends the scammer that person's financial reputation. The mule also gives a criminal access to services that may be difficult to obtain from abroad US Checking accounts, payment apps, cashier's checks, cash withdrawals, package delivery addresses, and cryptocurrency kiosks. The overseas organizer can direct all of those activities without appearing at a bank or showing identification.
[00:13:30] Speaker B: Speed matters, too. Once a victim reports fraud, banks may try to recall or freeze the payment. A mule can receive the money during US Banking hours and move it within minutes or hours, splitting it among accounts, withdrawing cash, buying cryptocurrency, or sending it to another mule. Every additional step makes recovery harder.
[00:13:48] Speaker A: Mules also create distance. The first name investigators see is usually the domestic account holder, not the overseas organizer. That forces banks and law enforcement to work backward through transfers, messages, aliases, and cryptocurrency wallets. The mule acts as a human firewall between the victim and the people directing
[00:14:06] Speaker B: the scheme, and mules are replaceable. If one account is frozen, the network can recruit another job seeker Romance scam victim, student or financially stressed person and redirect the next payment. That constant supply of ordinary looking accounts allows one overseas group to target many victims at the same time.
[00:14:24] Speaker A: So the mule is not a minor side player. The mule solves the scammer's hardest problem. Turning a victim's traceable domestic payment into money the overseas organization can control.
Without that bridge, many scams would be slower, easier to detect and much harder to cash out.
[00:14:41] Speaker B: To see how this works in practice, let's trace a step by step transaction to show how $100,000 stolen from a victim actually moves through the American banking system and vanishes offshore.
[00:14:53] Speaker A: Step one is the initial compromise. Imagine a retiree in Ohio named Robert who receives a pop up on his computer screen warning him that his bank account has been compromised. Frightened, he calls the number on the screen. The scammer on the phone, pretending to be a bank fraud specialist, convinces Robert to wire $100,000 to a safe holding account to protect his funds. Robert initiates the wire, sending the money to a domestic business checking account belonging to a single member LLC in Florida who set up by a money mule.
[00:15:23] Speaker B: Step two is rapid fragmentation and layering.
The moment that $100,000 wire hits the Florida account, the clock starts ticking for the criminal syndicate. They know Robert might realize he was tricked within 24 to 48 hours and ask his bank for a wire recall. To make the money impossible to recover, the syndicate commands the mule to immediately break up the cash. $10,000 is sent across multiple Zelle accounts belonging to secondary mules. $20,000 is routed through Cash App and Venmo handles. The remaining $70,000 is wired to a secondary bank account held by a witty mule.
[00:15:59] Speaker A: Step three is the cash conversion and cryptocurrency cutoff. The secondary mules are directed to withdraw cash or use debit transfers at local retail stores, gas stations or convenience stores equipped with bitcoin kiosks or ATMs. The scammer sends the mule a QR code via an encrypted app. The mule feeds cash directly into the bitcoin kiosk or executes a transfer. Scanning the scammer's QR code, the machine converts the domestic cash into Bitcoin or tether and broadcasts the transaction directly onto the blockchain.
[00:16:31] Speaker B: Within seconds, those funds enter an unhosted cryptocurrency wallet controlled by the syndicate in another country. Once on the blockchain, the funds pass through decentralized mixers or non KYC exchanges that that do not enforce identity verification at that point, the domestic audit trail is effectively broken and the victim's money is out of reach of traditional bank recalls.
[00:16:54] Speaker A: Timing is especially revealing. A legitimate business normally holds money to pay employees, buy inventory or deliver a service. A mule account behaves more like a pipe. Money arrives from a stranger and leaves almost immediately, often in several forms. That speed and repetition can expose the pattern.
[00:17:14] Speaker B: People often ask why banks don't instantly stop these transactions as they happen. The reality is that banks are constantly monitoring accounts under the Bank Secrecy Act. But scammers design their operational instructions specifically to exploit timing delays in automated banking systems.
[00:17:30] Speaker A: Financial institutions use anti money laundering monitoring to spot unusual behavior when activity raises concern. A bank may file a suspicious activity report or SAR with FinCEN. During my time as a Treasury Department Special Agent, I reviewed these reports regularly.
[00:17:48] Speaker B: Didn't you also participate in suspicious activity review teams during your time as a special agent? What were these so called suspicious activity review teams, Nick?
[00:17:57] Speaker A: Sure. In simple terms, a suspicious activity review team brings together people from law enforcement, financial regulators, and sometimes prosecutors to compare notes about unusual financial activity. Banks file reports when transactions do not fit a customer's normal behavior or appear connected to fraud, money laundering or another crime. The team reviews those reports, looks for repeating names, accounts, addresses, businesses and transaction patterns, and decides whether the information may support an existing investigation or justify a culture. Look, the report itself is not proof that anyone committed a crime. It is more like a lead that helps investigators see connections they might otherwise miss.
[00:18:37] Speaker B: Did those teams actually help develop cases?
[00:18:40] Speaker A: They certainly did. We saw potential activity ranging from narcotics trafficking to elder fraud. The reports helped us identify patterns and connect information that might otherwise have remained scattered across different institutions.
These reports identify millions of dollars dollars if not billions in money movement both domestically and internationally. They are filed on a regular basis as required by law.
[00:19:03] Speaker B: Interesting. So, Nick, I saw recent reports that bank of America was fined $1.21 billion by the U.S. treasury Department.
What was that penalty you're fined for?
[00:19:15] Speaker A: Glad you asked, Sue. That penalty was issued for widespread violations of anti money laundering and sanctions laws, specifically for failing to report more than $5 billion in suspicious customer transactions related to national security risks and illicit finance networks. I won't go into any more details in this episode because that whole fiasco will be covered in an upcoming episode of behind the Scams. But back to our story. A first red flag that banks might witness is the account's pass through activity. If an account normally holds a balance of $1,000 and has predictable monthly transactions and suddenly receives a $50,000 wire from an unrelated person across the country, that's an immediate red flag. If that $50,000 is moved out within hours through multiple peer to peer apps or cash withdrawals, automated systems flag it for human review. Second is what is known as structuring. Federal law under Title 31 requires financial institutions to file a currency transaction report for any cash transaction exceeding $10,000.
Scammers explicitly instruct their mules to withdraw or transfer money in smaller increments like 8500 or 9200 to stay just under that threshold. However, deliberately breaking up transactions to avoid reporting is itself a federal crime known as structuring under 31 USC section 5324, and it is one of the easiest patterns for bank algorithms to detect.
[00:20:39] Speaker B: Third is mismatched corporate profiles. Scammers often instruct mules to open small business bank accounts such as a single member llc, claiming it's for consulting or e commerce. But when bank compliance teams look at the account history, they see no normal business expenses like payroll, software, subscriptions or inventory purchases. Only large incoming wires from individuals, followed immediately by outgoing transfers to crypto exchanges or peer to peer payment handles.
[00:21:07] Speaker A: A fourth red flag is inconsistent customer behavior.
The account holder may arrive at a branch visibly coached on the phone, be unable to explain who sent the money, or repeat a rehearsed story. That changes when a teller asks basic questions.
They may insist that a transaction is urgent, refuse to identify the supposed employer or client, or become unusually focused on exactly when funds will become available.
[00:21:36] Speaker B: A fifth indicator is channel hopping. The customer receives a wire, attempts a large cash withdrawal, then pivots to cashier's checks when questioned, and finally tries a crypto kiosk or a peer to peer app. Each method alone can be legitimate. The risk comes from the sequence, the speed, and the lack of a believable economic reason.
[00:21:56] Speaker A: Banks also compare the parties. Is a personal account receiving payments from unrelated people in several states? Are memos vague or inconsistent with the account holder's occupation? Are funds repeatedly sent to the same wallet or foreign beneficiary after arriving from different victims? Network analysis can reveal that accounts that appear unrelated are serving the same criminal pipeline.
[00:22:19] Speaker B: Importantly, a bank alert is not a criminal conviction. Monitoring systems generate leads and analysts examine the surrounding facts. A legitimate customer may have an unusual transaction with a reasonable explanation nation. What raises concern is a pattern inconsistent stories, rapid movement, fabricated documents, repeated warnings or transactions that make no sense for the stated business.
[00:22:44] Speaker A: When federal law enforcement and forensic accountants trace these multi million dollar schemes backward from offshore wallets, the paper trail Almost always stops at the domestic bank account of the money mule. Unwitting mules often assume that if law enforcement contacts them, they can simply explain that they were fooled by a remote job posting or an online relationship and avoid trouble.
Claiming ignorance does not automatically prevent prosecution.
Depending on the conduct, annoying mule may face money laundering, conspiracy, wire or mail fraud, bank fraud, Identity theft, structuring, or false statement charges.
Prosecutors may also rely on willful blindness when someone recognizes obvious warning signs but deliberately avoids asking questions while continuing to profit.
A clear example is the case of Sherry l. Reeves of Kennett, Missouri. In June 2020, Reeves opened an account at a Bank of America branch in Jonesboro, Arkansas. Before October of that year, she added the fraud victim's name to the account. Her co conspirators then used stolen account information to move $565,000 from the victim into Reeves account in three electronic transfers.
And a lot of times, these mules
[00:23:58] Speaker B: aren't acting with as much knowledge as Reeves was. And sometimes the paper trail leads to a completely different type of scam.
In August 2018, the FBI launched a multi state investigation into an online romance scam. And that began, right, with a simple Facebook friend request.
[00:24:16] Speaker A: I mean, sue, how. How often have we seen this start off with an online relationship?
[00:24:20] Speaker B: I mean, unfortunately, in most cases that we come across, it seems every time, right.
[00:24:27] Speaker A: A tale as old as the Internet itself.
[00:24:30] Speaker B: And this one was no different.
[00:24:33] Speaker A: What happened in this case?
[00:24:34] Speaker B: So, a widower in her 60s, she was messaged by someone she believed was a man named Richard Evans. And after six months of building that bond through the computer, Evans finally told her that he was traveling for work and asked her to do him a simple favorite. He said, can you deposit a work check into your own account and then just send it off to a co worker?
[00:24:55] Speaker A: And the amount was for what?
[00:24:57] Speaker B: So on the surface, that check seemed legitimate, Right? It was like any other check. But the deposit, which was for $17,400, ultimately bounced, and the woman was held responsible.
[00:25:09] Speaker A: And this wasn't an isolated case.
[00:25:11] Speaker B: No. So when federal agents investigated further, they found a network of people who were also deceived into being money mules. And these mules were essentially the reason the scam artist was able to stay untraceable for years.
[00:25:23] Speaker A: I mean, sue, what you're describing is a process that criminals use on a. On an industrial scale. And unfortunately, it's more common than people think.
[00:25:31] Speaker B: Yeah, and as you mentioned in that story, prosecutors, they often rely on this quote, unquote, willful blindness because they're Seeing that people, they recognize the obvious warnings that and they're deliberately avoiding asking questions or continuing to profit from it.
[00:25:46] Speaker A: And a clear example of that was the case of Sherry L. Reeves of Kenna, Missouri.
[00:25:51] Speaker B: Right. So back in June 2020, Reeves opened an account at a Bank of America branch in Jonesboro, Arkansas. Now, before October of that same year, she added the fraud victim's name to the account. And then her co conspirators, they used that stolen account information to move $565,000 from the victim into Reeves account in three electronic transfers. So quite a bit of money.
[00:26:14] Speaker A: Reeves disbursed the money through cashier's checks obtained in Tennessee and Arkansas and through a coin flip cryptocurrency ATM in Duncan County.
[00:26:24] Speaker B: She also shared her account information and withdrew or attempted to withdraw proceeds in cash or by check.
Crucially, the Justice Department says she could continued assisting financial crimes even after the FBI warned her.
[00:26:38] Speaker A: Reeves pleaded guilty to aiding and abetting bank fraud, conspiracy to commit wire and mail fraud, and wire fraud.
In May 2025, the court sentenced her to 15 months in federal prison, five years of supervised release, and $565,000 in restitution to bank of America.
[00:26:57] Speaker B: At the other end of the spectrum is Chukwudi Michael Okwara of Charlotte.
Prosecutors said he used fake documents and false or stolen identities to open multiple mule accounts for business email compromise scams. Six companies were tricked into sending about $2 million to accounts he controlled.
[00:27:16] Speaker A: Once the wires landed, Okora did not let the money sit.
Within days, he made large cash withdrawals and sent additional wires to other accounts under his control, using false identities to conceal the trail.
A federal jury convicted him of money laundering, lying to a financial institution, and aggravated identity theft.
[00:27:36] Speaker B: In August 2022, he was sentenced to 13 years in federal prison. That case shows what a fully knowing mule operation can look like. Manufactured identities, multiple accounts, rapid withdrawals, and repeated efforts to disguise who controlled the money.
[00:27:51] Speaker A: These cases show a progression. White continued after banks warned her.
Marcus and Zawocki continued after federal agents warned them.
Reeves kept assisting after an FBI warning. Okwara used false identities from the start.
Different paths, but each additional warning lie, account or transfer made the claim of innocence harder to sustain.
[00:28:15] Speaker B: Being deceived is not the same as intentionally helping criminals. The turning point is what someone does after the warning signs become clear. Stop, contact the bank and report the situation, creating cover stories, opening replacement accounts or continuing after explicit warnings points in the opposite direction.
[00:28:36] Speaker A: The consequences can include prison, supervised release, fines, restitution, closed accounts, and long term difficulty Obtaining banking services.
The sooner a person stops, the better the chance of limiting the damage.
[00:28:50] Speaker B: So how can you tell if someone you care about may be acting as a money mule? Look for a cluster of changes rather than one isolated event. A new online relationship or remote job may suddenly be followed by unfamiliar deposits, urgent trips to the bank, purchases of gift cards or cryptocurrency, or requests to
[00:29:10] Speaker A: use a family member's account.
Another warning sign is secrecy your love. One may become guarded about a new employer or online companion. Insist that the arrangement is confidential or say the bank doesn't understand.
They may receive instructions during transactions, repeat scripted explanations, or become anxious when a transfer is delayed.
[00:29:33] Speaker B: Watch for money that does not fit the person's normal life. Deposits from strangers, checks made out to unfamiliar businesses, multiple payment app accounts, unopened, packages being reshipped, or cash moving in and out without a clear reason.
The person may keep a small percentage and send the rest elsewhere, believing that commission proves the job is legitimate.
[00:29:54] Speaker A: Emotional changes matter, too. Someone being manipulated may defend the recruiter intensely withdraw from family, or become fearful that they will lose a relationship or job if they stop.
They may also say they must complete one last transfer to unlock a payment. Protect the other person or avoid getting in trouble.
[00:30:14] Speaker B: If you are concerned, begin without accusation. Try I'm worried someone may be using your account to move stolen money. Can we look at the messages and transactions together?
Focus on a behavior, not the person's judgment. Shame can make someone hide the activity and cling more tightly to the skin.
[00:30:33] Speaker A: Scammer Ask simple questions. Who sent the money? Why can't they use their own account?
Why must it be forwarded immediately? Why is your loved one being paid just to move it? Why are they being told not to speak with the bank or family?
If the answers are vague, keep changing or rely on secrecy and urgency. Stop the next transaction and contact the bank's fraud department together.
[00:30:58] Speaker B: The immediate goal is to interrupt the scammer's control. Sit with your loved one while they call the bank, pause pending transfers, and stop communicating with the recruiter. If they resist, ask them to wait 24 hours before moving any more money and to let an independent bank employee review the situation.
[00:31:14] Speaker A: Expect the scammer to push back. They may threaten arrest, claim an emergency, promise a large reward, or accuse the family of ruining everything.
Warn your loved one about those tactics in advance so the next message feels less convincing. The pressure itself is evidence that this is not a normal job or relationship.
[00:31:35] Speaker B: Keep the door open.
People often stay involved because they fear humiliation or punishment. Tell them. You are not the first person this has happened to and we can deal with the next step together. A calm, supportive response makes it more likely they will disclose every account, payment, app and instruction before more money moves.
[00:31:54] Speaker A: The clearest warning is simple Legitimate employers and genuine romantic partners do not need your personal bank account to receive money from strangers. If a loved one is being paid to forward funds, buying cryptocurrency for someone else, reshipping packages, or opening account on another person's instructions, treat it as an urgent money mule.
[00:32:15] Speaker B: Warning the key takeaway is that global cybercrime depends on all ordinary domestic accounts. Whether the mule is a trusted professional, a job seeker, or someone emotionally invested in an online relationship, the account gives the scammer credibility, speed and distance from the victim.
[00:32:33] Speaker A: Remember the golden rule. Legitimate employers and genuine online acquaintances do not need your personal account to receive money from strangers. If someone asks you to forward funds, buy cryptocurrency, purchase gift cards, reship packages or or lie to a bank, stop her families.
[00:32:51] Speaker B: Watch for the pattern a new online job or relationship, unexplained deposits, instructions to forward most of the money, secrecy, urgency and pressure to distrust the bank or family.
Respond calmly, pause the next transaction and contact the bank together.
[00:33:10] Speaker A: Thank you for tuning in to behind the Scams. Be sure to subscribe, leave us a review and share this episode with anyone who might benefit from knowing these warning signs.
[00:33:19] Speaker B: Stay alert, keep your account secure, and we'll see you next time on behind the Scams. Bye for now.