Episode Transcript
[00:00:00] Speaker A: This one hits close to home. Or at least former home, since I lived in Vallejo many years ago and know lots of people from that area of Northern California.
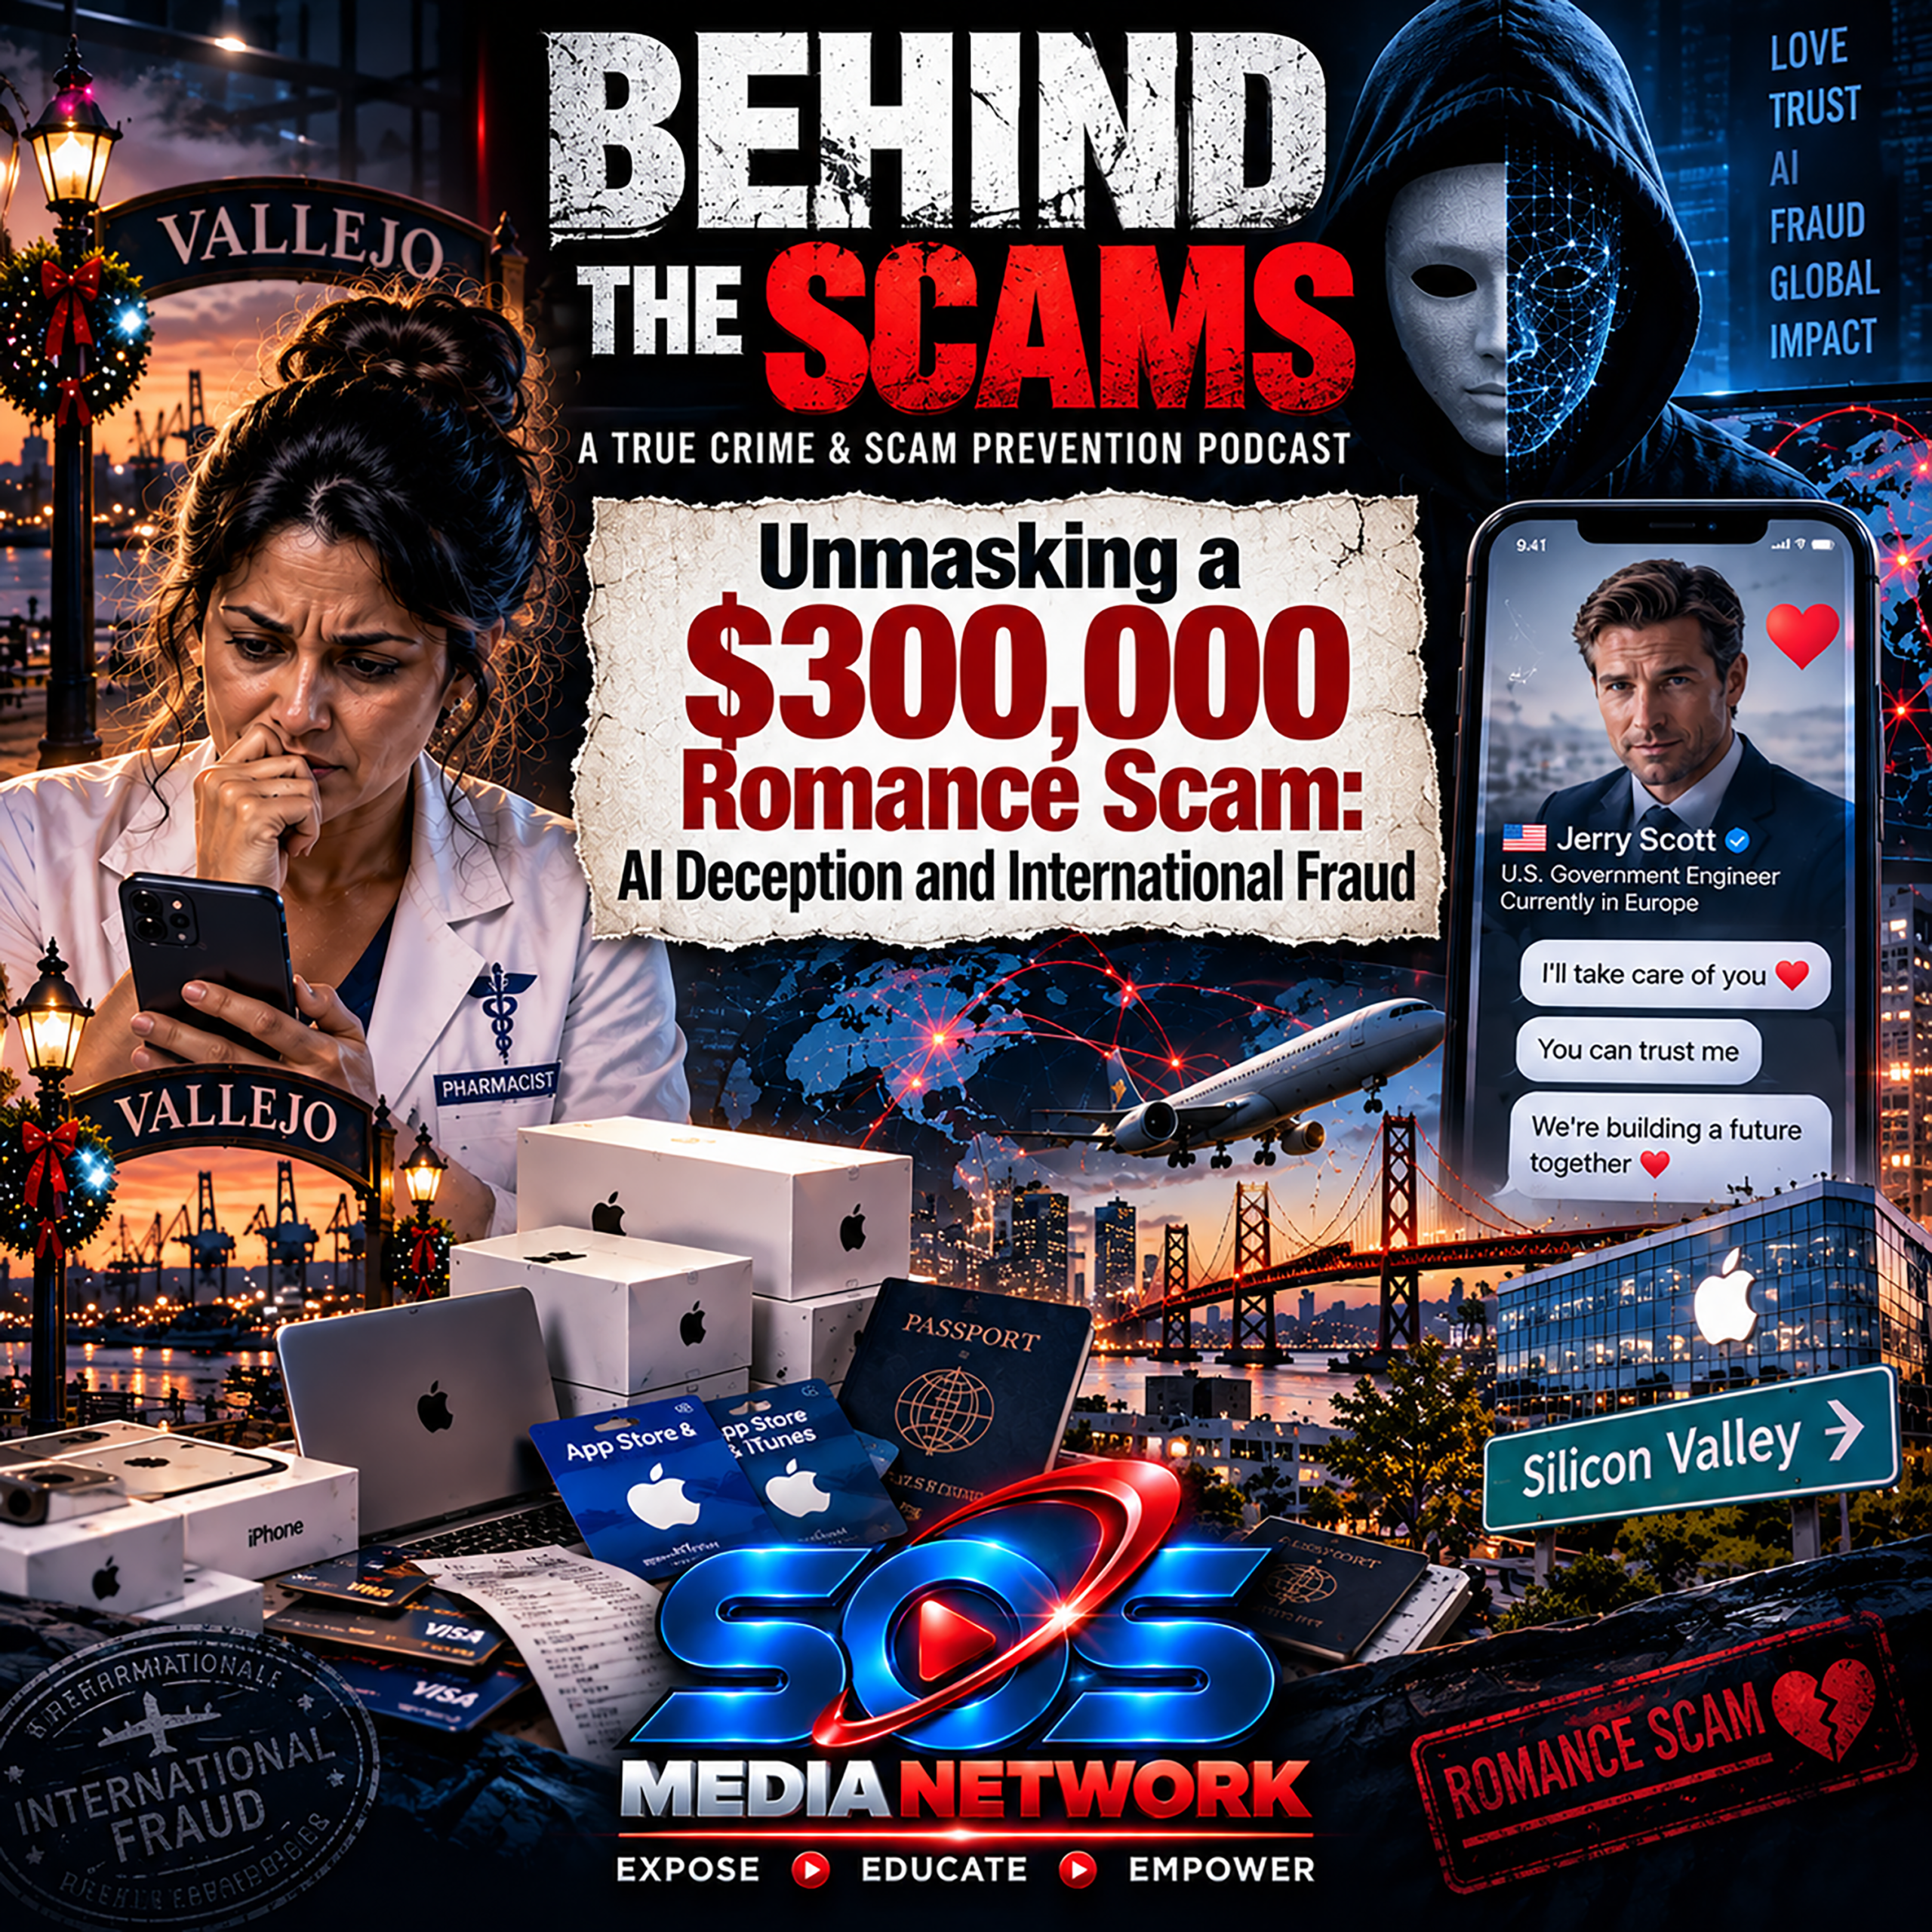
And when I picture Vallejo in December, I picture the waterfront, the old neighborhoods, holiday lights across the Bay Area. Not a pharmacist racing from Apple store to Apple store, putting hundreds of thousands of dollars on credit cards for a man she had never met.
[00:00:29] Speaker B: It hits close to home for me, too.
I served as a special agent in Northern California not far from Vallejo, and worked a lot of narcotics cases as well as high technology crime investigations in nearby Silicon Valley.
[00:00:44] Speaker A: So between the two of us, we know the neighborhood. And you know what happens when a criminal network combines old fashioned manipulation with new technology.
[00:00:54] Speaker B: Exactly. The tools evolve, but the underlying business is familiar.
Identify vulnerability.
Establish trust. Move value. And put as much distance as possible between the people directing the crime and the person left holding the loss. Her name is Raza. She was 37, a trained pharmacist and accustomed to work where precision is not optional.
Dosages matter. Interactions matter. Identity checks matter. By day, she operated in a world of safeguards. At night, over roughly 30 days, she entered a different system. One designed to make every safeguard look as though it had already been satisfied.
[00:01:40] Speaker A: Instead of filling prescriptions, she was filling shopping carts, MacBooks, iPhones and Apple gift cards. Five laptops became more devices, then more cards, then another store.
Each approval beep sounded like proof that the plan was working.
[00:01:57] Speaker B: But every beep was another heartbeat in a 300,000 gamble.
Raza believed a high level US government engineer stationed in Europe was taking care of her. In reality, she was financing an international criminal supply chain.
[00:02:13] Speaker A: And just so we're clear, if your new boyfriend's love language is enterprise grade hardware procurement, that is not romance. That is an unpaid logistics internship.
[00:02:27] Speaker B: No benefits, no vacation days. And the employee handbook is apparently just a shipping label.
[00:02:33] Speaker A: Picture the camera lifting off Vallejo's waterfront at dusk. The Mare island cranes in silhouette.
Car lights threading onto the freeway. The bay reflecting the last of the evening sky.
Then it tracks south past bridges and cities toward the glass campuses and glowing screens of Silicon Valley.
[00:02:54] Speaker B: I traveled that corridor as a special agent. On one end, narcotics cases built on couriers, cash, aliases and pressure. On the other, high technology crimes built on accounts, devices, data and speed.
But the line between them was never as bright as the lights made it look. The technology changed. The criminal instincts did not.
[00:03:20] Speaker A: And Raza's story travels that same route in reverse. Silicon Valley hardware flowing north into her hands in Vallejo. Then disappearing into a network that reached far beyond California.
A relationship on a screen became a credit card balance, a stack of sealed boxes, and an international supply chain.
[00:03:43] Speaker B: Before we follow those boxes out of the country, we have to rewind to the quiet moment before the first purchase, before the first payment appeared, and before a polished stranger named Jerry Scott asked for anything that sounded dangerous. To understand why the scam worked, we need to begin before the first purchase.
Raza had come out of a nine and a half year relationship.
She wanted some of the financial stability she had known, but not the volatility of traditional dating.
She tried bumble, then moved to the sugar dating platform, seeking arrangements.
She did not describe herself as reckless.
Quite the opposite. She gave the experiment a three month deadline and approached it almost like a project.
[00:04:29] Speaker A: A defined goal, a timeline. And presumably no spreadsheet titled Men who Need me to buy 47 iPhones.
[00:04:37] Speaker B: If that spreadsheet exists, the first column should be absolutely not. Not yet. Less than a month in, she matched with Jerry Scott.
His profile was restrained. No rented sports car, no champagne tower. No stacks of cash arranged like a low budget music video.
Just a polished bathroom mirror selfie, Tailored suit, tie, dark blonde hair, blue eyes.
[00:05:06] Speaker A: That restraint mattered. Flashy might have looked fraudulent. Ordinary competence looked safe.
[00:05:12] Speaker B: Jerry said he was a US government engineer assigned to Europe. His offer was 400 every two weeks in exchange for digital companionship. No strings attached.
That amount was important.
It was generous enough to be interesting, but not so extravagant that it sounded absurd.
Fraudsters calibrate the first proposition often has to survive the target's internal smell test.
[00:05:41] Speaker A: And the setting created its own false sense of safety. On a sugar dating site, financial arrangements are part of the premise. A conversation about money does not arrive wearing a red flag. It arrives wearing the platform's name tag.
[00:05:57] Speaker B: Exactly. The transaction feels negotiated. The victim feels like a participant with agency, not a target being pressured. That is the first theme in this case.
The weaponization of a supposedly safe consensual transaction. Jerry did not have to invent money as a topic. The platform had already normalized it.
[00:06:19] Speaker A: So the platform supplied the financial vocabulary and Jerry supplied the fiction.
[00:06:24] Speaker B: Exactly. He didn't have to break the ice. The business model had already put it in a cocktail glass.
[00:06:30] Speaker A: Then Jerry asked for something. No legitimate benefactor.
Raza's online banking username and password. He said he wanted to pay off her debt and make transfers easier.
[00:06:42] Speaker B: Raza refused at first. That refusal is important.
She recognized the danger. Her skepticism was functioning.
Jerry's job was not to create trust from nothing. It Was to give her one piece of evidence that would let her override her own warning.
[00:07:01] Speaker A: The evidence was a five second selfie video.
The man from the photograph smiled into the camera and said, hey, what did you do today? This is what I did. Merry Christmas. That was it. Five seconds.
[00:07:15] Speaker B: But it was living media.
It moved. It spoke. It appeared casual and current.
For someone who wanted verification, the clip felt stronger than a static photo.
It answered the question she was asking.
Is there a real man behind this account?
Without answering the question she needed to ask. Is this man Jerry Scott? Did he make this video for me? Does he control the money he claims to control?
[00:07:43] Speaker A: It was synthetic trust. Before the money became synthetic, too. The clip did not prove the story. It merely gave the story a face.
[00:07:53] Speaker B: In fraud investigations, that distinction comes up constantly. Verification has layers. A face can be real while the identity is false. A check can be real while the account is stolen. A payment can appear in an app. While the money does not exist.
The scammer survives in the gap between appearance and final settlement.
[00:08:14] Speaker A: After that video, Raza's view shifted. Giving access no longer felt like surrendering control.
It felt like participating in a win win arrangement. She handed over her bank usernames and passwords.
[00:08:30] Speaker B: Once Jerry had the credentials, he could see which cards had room, which balances could be manipulated, and. And how quickly Raza responded when a payment appeared.
[00:08:40] Speaker A: So he wasn't merely inside the bank account. He was watching her. Decision making in real time.
[00:08:46] Speaker B: Exactly. The romance conversation had become financial reconnaissance. Once inside the accounts, Jerry could see the map. Available credit balances, debt, and how much borrowing room Raza had.
Then came the favor he said he needed. Year end gifts for employees.
But European transaction limits prevented him from purchasing them himself. Would she buy the merchandise in California? He would reimburse her immediately.
[00:09:14] Speaker A: A US government engineer with international responsibilities, yet somehow defeated by the Apple checkout page.
[00:09:22] Speaker B: Apparently he could engineer for the government, but add to bag was beyond his security clearance. The first shopping list sounded manageable.
Several laptops, phones, gift cards. Jerry supplied shipping instructions. Raza used her own credit cards and watched for reimbursement. Then the crucial illusion appeared. Payments hit her card accounts, balances dropped. Available credit returned.
[00:09:50] Speaker A: Walk us through the reimbursement trick. Because this is where the screen seemed to confirm Jerry's story.
[00:09:56] Speaker B: A stolen account number initiated a payment.
Roz's card interface reflected it. She saw the balance fall and her credit line reopen.
Before the originating bank could reject the debit, Jerry sent another shopping list.
Each cycle converted the same temporary illusion into more Real merchandise.
[00:10:19] Speaker A: From her point of view. The system had now confirmed Jerry twice.
First the video, then the money. She bought devices. He paid the card. The arrangement appeared to work. Her app was essentially saying, nothing to worry about.
Unfortunately, banking apps are excellent at displaying transactions and terrible at leaning across the screen to whisper. Maybe give this a few days.
[00:10:46] Speaker B: Except those payments were initiated with stolen account and routing numbers.
This is the ACH Float trap.
A banking app may credit an initiated payment and restore available credit before the banks finish validating the source.
The interface says payment received.
The underlying system has not yet said money finally settled. That gap can last days. More than enough time for a scammer to push the next purchase.
[00:11:16] Speaker A: So the cleared balance was not proof of wealth. It was borrowed credibility. And the borrowing happened inside Raza's own banking app.
[00:11:26] Speaker B: Right.
Jerry had found a way to make trusted institutions deliver his lie for him.
A fake email might be questioned. A card balance displayed by the issuer feels authoritative.
The criminal did not need to counterfeit the app.
He exploited the timing of the payment system behind it.
[00:11:48] Speaker A: A tiny phrase with the confidence of a game show host. Congratulations. You may now lose the same money twice. The lists grew. Five laptops became dozens of devices.
Raza moved across Northern California, Apple Stores using one card and then another, repeatedly converting credit into compact, valuable merchandise.
At some point, employee gifts. Stop sounding like generosity and start sounding like the IT department for a small nation.
[00:12:21] Speaker B: A small nation whose entire workforce apparently wanted the same Christmas present. And notice the pace.
Approximately $300,000 was extracted in about 30 days.
That speed was not incidental. It was protection.
Every day the false payments remained unreversed was another day the same credit could be reopened and used again.
The syndicate was racing the settlement process,
[00:12:49] Speaker A: and she began taking stock of every card she owned, moving from account to account as limits reopened and then disappeared again.
[00:12:57] Speaker B: That tells us this was not one catastrophic checkout. It was a coordinated run across multiple cards, multiple stores, and multiple days at the same time.
[00:13:08] Speaker A: Jerry accelerated the relationship. He said, I love you. He talked about buying a home together in California. He promised to finance her return to graduate school. The purchases became entangled with a future she could picture.
[00:13:24] Speaker B: This is where outsiders often make the mistake of separating the romance from the financial transactions.
The romance was not decoration.
It was the enforcement mechanism.
By the peak of the shopping, questioning the next order could feel like questioning the relationship. The house, graduate school, even a future marriage.
[00:13:44] Speaker A: And each completed purchase created commitment. If you have already bought five laptops, buying five more may feel less like a new decision than Finishing the job.
[00:13:55] Speaker B: That is the foot in the door effect. Join to sunk cost.
The first request tests compliance. The apparent reimbursement rewards it. The second request feels validated by the first.
Soon the victim is no longer deciding whether to trust the stranger. She is trying to protect the value of every decision already made.
[00:14:17] Speaker A: Why not just steal cash? Why send somebody into stores for physical hardware?
[00:14:22] Speaker B: High end electronics are global cash with serial numbers.
A laptop or phone is compact, expensive, standardized, easy to ship and easy to resell.
It can cross borders in a box and be converted into local currency in a market where the original victim, retailer, bank, shipper and buyer may all be in different jurisdictions.
[00:14:48] Speaker A: Which means Raza was not merely losing money. Without knowing it, she had been turned into the Syndicate's purchasing department.
Her clean credit bought legitimate goods. Her physical presence satisfied the retailer. Her authorized signature shifted the loss back on to her. A purchasing department, a shipping department, and without knowing it, the only person in the organization expected to pay the bill.
[00:15:15] Speaker B: That is hardware laundering. The criminals started with stolen banking credentials that could be detected and reversed.
Through Raza, they converted that fragile value into real devices.
Once received, those devices could be moved, sold and dispersed. The electronic payment disappeared. The electronics did not.
[00:15:37] Speaker A: The gift cards served a different purpose from the laptops and phones, didn't they?
[00:15:41] Speaker B: They did. A gift card code can be photographed, transmitted and redeemed quickly without shipping the card very far.
The Syndicate was harvesting two kinds of portable value devices for resale and stored value for rapid conversion.
[00:15:58] Speaker A: In mid December, the payments began to reverse. The source accounts were fraudulent. One balance returned, then another.
Available credit vanished. Cards froze. In a matter of days, more than $300,000 rushed back onto Roza's accounts until
[00:16:17] Speaker B: the middle of the month. When the reimbursements did not merely slow down, the banks unwound them. And the holiday shopping spree became a wall of restored debt. Imagine watching debt you thought had been erased reappear line by line. The merchandise was gone, the payments were gone, and the legal obligation remained. Her credit score collapsed. But Jerry did not disappear immediately because the Syndicate still believed there might be value left to extract.
[00:16:48] Speaker A: First came the banking error. Jerry said his international bank had flagged the transfers because he was overseas. In scam translation, the lie had failed. So he added geography.
[00:17:01] Speaker B: Right when the money vanished, Jerry did what bad contractors do. Blamed the bank, blamed the border, and promised the check was in the mail. Then he sent a third party check, supposedly from a friend, to cover the debt. It bounced.
That check served two purposes. It bought time, and it gave Raza, a new reason not to accept that everything before it had been fraudulent.
[00:17:29] Speaker A: Finally came Cryptocurrency. Jerry pushed her to open fintech apps and send crypto to unlock funds overseas.
By then, the request was no longer supported by hope alone. It was supported by panic. If one more transfer might recover 300,000, saying no could feel like choosing to lose it all.
[00:17:51] Speaker B: This is a critical fraud dynamic. The same person can be groomed first by reward and later by loss. Early on, Jerry promised comfort. At the end, he promised rescue. Both promises drove money in the same direction.
[00:18:06] Speaker A: So when Jerry the provider stopped working, he rebranded as Jerry the Rescue Department.
[00:18:12] Speaker B: Same desk, same crook, new hold music.
[00:18:14] Speaker A: Raza turned over messages, shipping receipts, and the transaction trail. The addresses Jerry supplied looked like domestic logistics businesses, exactly the kind of places that can make a shipment seem routine.
[00:18:29] Speaker B: One destination was prime logistics on the seventh floor of a New York building.
When investigators examined it, they found abandoned, silent hallways.
Some office doors had their handles removed. The building manager said the tenants had left months earlier.
[00:18:48] Speaker A: Another was Overland Global Logistics outside Houston. That location was a bear with unlocked room containing little more than a phone charger, a dirty pillow, and a pile of missed delivery notices for Jerry's recipients.
[00:19:04] Speaker B: A collection point does not need a reception desk or a conference room. A runner needs an address, a delivery window, and enough time to move the box before anyone asks what the company actually does. If your Global Logistics headquarters contains a dirty pillow and fewer office supplies than the average glove compartment, it is not a headquarters, it is a clue. Those rooms were not corporate operations in the ordinary sense. They were collection points, thin domestic shells in a larger international chain. Runners intercepted packages in New York and Texas. The goods were consolidated and moved onward.
[00:19:44] Speaker A: Investigators involving the U.S. secret Service and Nigerian local police followed serial numbers from the devices Raza purchased. The trail led by air freight from Texas to the airport in Lagos, Nigeria, and then to local black markets.
[00:20:02] Speaker B: Collection, transit, liquidation, that is the supply chain. The scammers did not need one person to perform every task. One operator groomed Raza. Other people controlled stolen bank data.
Domestic runners received packages. Freight moved them overseas. Resellers turned hardware into cash. Compartmentalization made the enterprise harder to see and harder to prosecute.
[00:20:28] Speaker A: A romance scam with runners, freight routes, Shell offices, and overseas resale. Jerry may have been imaginary, but his distribution network had better logistics than some actual retailers.
[00:20:42] Speaker B: True, the boyfriend was fictional. The supply chain was fully staffed, and
[00:20:47] Speaker A: none of the $300,000 in merchandise came back. By the time the fraud was recognized, the devices had already been absorbed. Into markets thousands of miles away.
[00:20:59] Speaker B: A reverse image search eventually exposed the identity behind the Christmas clip. The man was Eric Powell, an innocent person whose photos and videos had been hijacked and recycled by fraud syndicates for years.
The face was genuine. The engineer was fiction.
[00:21:17] Speaker A: That matters because identity theft in a romance scam can create two victims. Raza lost money and trust.
Eric's face was turned into criminal infrastructure, Appearing in conversations he never had and making promises he never made.
[00:21:36] Speaker B: We sometimes talk as though a reverse image search tells us whether a person is real.
The better question is whether the image belongs to the person using it.
In this case, Jerry Scott was a digital ghost stitched together from stolen media, A plausible profession and practiced responses.
[00:21:57] Speaker A: Before this story grows another layer of mystery, lets put the facts on one side of the table and the assumptions on the other. What can we actually prove?
[00:22:08] Speaker B: We can prove that Jerry Scott was a fabricated identity.
The photos and Christmas video belonged to Eric Pal, an innocent person whose media was used without permission.
We can also prove that Raza was directed to shipping points in New York and Houston, plus places whose corporate image did not survive a visit to the premises.
[00:22:30] Speaker A: Right. The letterhead said global Logistics. The room said please ignore the missing door handle.
[00:22:37] Speaker B: And the hardware left a harder trail than Jerry did. Investigators followed device serial numbers through Texas, onto air freight bound for Lagos, Nigeria, and into local resale markets. None of the merchandise was documented as recovered. Those points are established.
[00:22:57] Speaker A: So the boxes checked in. Jerry never did what remains unknown.
[00:23:01] Speaker B: His real name, his physical location. Whether one person handled the messages or several operators worked the Persona in shifts. The Lagos trail tells us where the merchandise went. It does not tell us where the person typing I love you was sitting.
[00:23:17] Speaker A: The merchandise had a passport. The boyfriend had a stage name.
[00:23:22] Speaker B: Precisely.
The public record also does not identify the domestic runners, the people supplying stolen bank data, the freight coordinators, or the overseas resellers. And it does not confirm arrests tied to the operators behind Jerry.
We can describe the machinery without pretending we know every mechanic.
[00:23:44] Speaker A: Financially, the confirmed picture is grim.
The payments were reversed, the merchandise was not recovered and no restitution was documented. But we cannot say she filed bankruptcy, settled the debt, received insurance proceeds, or later recovered money through a lawsuit.
[00:24:03] Speaker B: Exactly. We don't know is not a weak ending. It is an honest boundary. The scammers built this case by making uncertainty uncertainty feel like proof.
We should not repeat their technique while telling the story.
[00:24:18] Speaker A: Authorities recognized Raza as a victim, not a co conspirator.
But that did not mean the debt vanished.
[00:24:26] Speaker B: She had physically entered the stores.
She had presented her own cards. She had authorized the purchases.
The fraudulent incoming payments were reversed, but the retail transactions were were legitimate. From the card issuer's perspective, there were no criminal charges against her and no simple legal mechanism forcing the banks to absorb the loss.
[00:24:51] Speaker A: That is a brutal distinction. Victim in the criminal investigation, debtor in the financial system.
[00:24:58] Speaker B: She was left negotiating emergency hardship arrangements with creditors. The available account says none of the merchandise was recovered and the fraudulent payments were reversed, leaving more than $300,000 in debt in her name.
It does not document that she recovered any money.
[00:25:17] Speaker A: And did she ultimately file for bankruptcy?
[00:25:20] Speaker B: We could not verify that from the available reporting. The documented outcome is hardship negotiations with creditors, frozen cards, damaged credit, no recovered merchandise, and no confirmed restitution.
Bankruptcy may be an understandable question at this scale, but we should not turn it into a fact without a reliable record.
[00:25:43] Speaker A: So the honest answer is stark zero. Documented recovery, six figures of debt, and an uncertain financial future.
[00:25:52] Speaker B: And another compelling point, the banks could reverse the stolen payments because those transfers were unauthorized at the source.
But Roz's store purchases were authorized by her.
The system could unwind the counterfeit reimbursement while leaving the genuine debt intact.
That asymmetry is the financial engine of the crime.
[00:26:15] Speaker A: The fraud vanished backward through the banking system. The bill only traveled forward to her. Look at how many systems the investigation had to cross.
Retailer records, card accounts, shippers, domestic collection points, international freight, foreign police, and overseas resale markets.
[00:26:37] Speaker B: Every handoff created another jurisdiction, another records request, and another delay.
Yet the debt did not scatter across that international network.
It remained concentrated in one place.
[00:26:51] Speaker A: Raza's reporting still matters, even when it does not produce an immediate refund.
The Federal Trade Commission explains that individual reports are shared through a database used by more than 2,000 law enforcement partners, helping agencies identify patterns and build cases. Although the FTC does not resolve each
[00:27:15] Speaker B: victim's loss directly, that is an important distinction. A report may not put money back into one account tomorrow, but the shipping address, recipient name, wallet device, serial number or phone number can connect one victim's case to a much larger operation.
[00:27:33] Speaker A: Nick, if you were sitting across from someone at the very start of a situation like this, before the first laptop, before the first bounced payment, what would you tell them?
[00:27:43] Speaker B: First, never give anyone your bank username, password verification code or remote access Credentials are not a way for someone to send you money. If a supposed benefactor needs to enter your accounts, the arrangement has already crossed the line from unusual to dangerous.
[00:28:03] Speaker A: If the relationship requires a password reset before the first date. The romance portion may be underperforming.
[00:28:10] Speaker B: That is a generous assessment. I would call it burglary with pet names.
[00:28:15] Speaker A: What if the payment is already showing on the card?
[00:28:18] Speaker B: Do not confuse posted with settled. Call the card issuer using a trusted number and ask whether the funds have been finally collected from the originating account.
If someone pays down your card and immediately tells you to spend the newly available credit stop, that is the signature pattern of an ACH float scam.
[00:28:41] Speaker A: In other words, the app may be showing confetti while the actual money is still circling the airport.
[00:28:47] Speaker B: Exactly. Wait until the money lands, clears customs and unpacks its suitcase.
[00:28:52] Speaker A: And if the purchase is going to a freight forwarder, mail drop or logistics
[00:28:56] Speaker B: company, treat that as a major warning. Ask why a wealthy person with customers, government contracts, international banking relationships, or a successful business needs a new online acquaintance to buy and ship high value electronics. If the explanation is frozen accounts, transaction limits, procurement rules or a broken payment system do not solve the problem for them.
Their inability to buy is not your emergency.
[00:29:27] Speaker A: Because my international banking system is down is not a reason for you to become a one person electronics wholesaler, especially
[00:29:35] Speaker B: when your entire compensation package is promises and tracking numbers.
[00:29:39] Speaker A: What about a selfie video or a live looking clip? That was the proof that changed everything for Raza.
[00:29:45] Speaker B: A real face does not prove a real identity.
A photo, voice or video does not establish who sent it and who owns it, where the person is, what job they hold or whether they control the money they claim to have.
Verify through independent channels. And even successful verification never justifies sharing banking credentials or becoming someone's purchasing proxy.
[00:30:13] Speaker A: So a handsome face saying Merry Christmas is evidence that a handsome face can say Merry Christmas.
[00:30:20] Speaker B: Correct. It does not come with an engineering license, a government badge, or audited financial statements. And when affection suddenly accelerates, slow the financial decisions down.
I love you. Marriage plans, a promised home, or an offer to pay for school can make skepticism feel like betrayal. It is not betrayal to wait, verify and involve someone you trust.
A legitimate relationship can survive a pause. A fraud operation usually cannot.
[00:30:51] Speaker A: If I love you and what is your credit limit? Arrive in the same week, perhaps let the first phrase marinate, preferably until the
[00:30:59] Speaker B: second phrase has been shown the door.
[00:31:01] Speaker A: And if money has already been lost,
[00:31:03] Speaker B: do not let the first loss recruit you into the second. A fake check, an unlocking fee, a cryptocurrency transfer, or a stranger promising recovery for an upfront payment is not a rescue plan.
Stop sending money. Preserve the evidence and bring in the bank, the retailer, law enforcement, and someone you trust the person who created the
[00:31:27] Speaker A: emergency is rarely the best candidate to
[00:31:30] Speaker B: operate the rescue boat, particularly when admission requires one more cryptocurrency payment.
[00:31:36] Speaker A: Let's make make this practical. Suppose a listener has received a payment, bought merchandise, or shared banking credentials. What should happen now?
[00:31:45] Speaker B: First, stop the movement. Do not buy, ship, transfer, deposit or convert anything else. Contact every affected bank and card issuer through a trusted number and ask for the fraud department.
Say that your credentials may be compromised and that payments may have originated from stolen accounts.
Ask whether any payment is fully settled, not merely posted or pending.
[00:32:11] Speaker A: Change passwords from a clean device. Enable multi factor authentication. Remove unfamiliar recovery emails or phone numbers, and check whether new payees, transfers or linked apps were added. Preserve screenshots before closing accounts. If the bank advises that it is
[00:32:31] Speaker B: safe to do so, contact retailers and shipping companies immediately. A package that has not been delivered may still be intercepted. Save order numbers, serial numbers, receipts, shipping labels, tracking histories, chat logs, profile links, phone numbers, email addresses, checks, account details and cryptocurrency transaction records.
Do not delete the conversation just because reading it is painful.
[00:33:02] Speaker A: Report the profile to the platform. Make a local police report file with the FBI's Internet Crime Complaint center and the Federal Trade Commission and give investigators the logistics trail, not just the romantic story. Addresses, freight companies, names on labels and device serial numbers may link your case to others.
[00:33:24] Speaker B: Finally, tell somebody you trust.
Shame creates delay, and delay benefits the criminal.
The first useful question is not how did you fall for this? It is what? Can we still stop?
Then watch for recovery scammers. Anyone demanding an upfront fee, tax, crypto deposit or secret payment to retrieve the money may simply be the next crew in line.
[00:33:49] Speaker A: If you are the relative or friend who discovers the situation, lower your voice before you raise your questions. The victim may still believe the person is real, may fear losing the relationship, or may be trying to recover the money without anyone finding out.
[00:34:06] Speaker B: Start with facts that can be checked together.
Has the payment for finally settled? Who owns the account that sent it?
Does the shipping address match a real operating business?
Can the person appear on a live call, respond to an unpredictable request, and verify identity through an independent channel? Even then, no verification justifies sharing credentials or acting as a financial proxy.
[00:34:37] Speaker A: And resist triumphant. I knew it. You may be correct, but being correct is not the same as being useful.
[00:34:43] Speaker B: Correct.
I told you so is not a fraud recovery tool, although families keep trying to download it. The goal is to replace the scammer's closed loop with a safer one victim trusted person, bank retailer, investigator Calm cooperation can save evidence, stop shipments and preserve whatever options remain.
[00:35:07] Speaker A: Vallejo may be my former home, but this case is not local in any meaningful sense. It began on a dating platform, moved through California stores, passed through ghost offices in New York and Texas, flew to Lagos, and ended in black markets where the hardware became cash.
[00:35:27] Speaker B: In roughly 30 days, a syndicate converted one person's trust and credit into more than $30,000 in portable assets. It used a stolen face to create synthetic trust, stolen bank data to create synthetic repayment, and legitimate stores to create real merchandise.
That combination is what made the scheme so devastating.
[00:35:51] Speaker A: So remember, a 5 second video is not identity video verification. A posted payment is not necessarily settled money, a shipping company is not automatically a real company, and a wealthy stranger who needs your credit card may be wealthy only in excuses affection.
[00:36:12] Speaker B: Is not verification available? Credit is not repayment.
And if someone else's financial problem requires your password, your card, your signature, and a cart full of MacBooks, you are not being taken care of. You are being positioned between the criminal and the loss.
[00:36:33] Speaker A: Before we go, a heartfelt reminder. Behind the Scams is part of the SOS Media Network. Powered by Stamp Out Scams. This work is made possible by people who believe that everyone deserves clear, trustworthy information and that scam victims deserve compassion, not judgment. If this episode helped you protect yourself or someone you love, please consider making a tax deductible donation to Stamp Out Scams.
Every contribution, at any level, helps us reach more families with the information they need before a scammer reaches them.
[00:37:12] Speaker B: Sue, I'm glad you mentioned that. The SOS Media Network we're proud to announce that SOS Media Network is now a registered trademark of Stamp Out Scams, officially granted by the United States Patent and Trademark Office.
We've used the name for the past several months while the application moved through the trademark process.
As of September 1, 2026, it is officially ours.
[00:37:39] Speaker A: That makes it official and gives us one more reason to keep building a trusted home for reporting, education, and conversations that help people recognize scams before the damage is done. I'm Sue.
[00:37:54] Speaker B: And I'm Nick. Thank you for listening. Thank you for supporting Stamp Out Scams and we'll see you next time on behind the Scams.